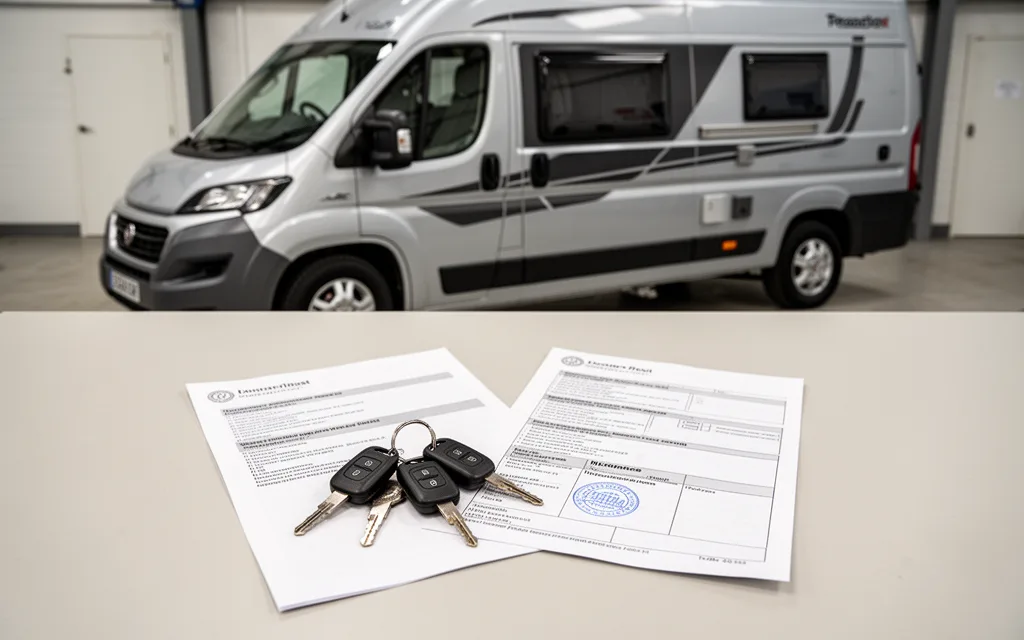
For UK van conversion project owners, securing the best van conversion insurance uk is crucial to protect your investment and ensure compliance with legal requirements. Unlike standard vehicle insurance, van conversions often involve custom modifications, specialist equipment, and unique usage scenarios—each demanding tailored coverage. Whether you’re building a mobile workshop, a living space, or a commercial unit, your policy must account for added components, higher liability risks, and potential income loss during repairs. The right insurance not only safeguards your asset but also provides peace of mind, ensuring your project remains viable amid unforeseen challenges. Prioritise policies that explicitly cover conversion-specific risks and align with your van’s intended use.
Understanding the Importance of Van Conversion Insurance in the UK
Van conversion projects in the UK involve significant modifications to vehicles, often altering their structural integrity, electrical systems, or safety features. Without proper insurance, these changes can leave owners exposed to legal and financial risks. Under the Road Vehicles (Construction and Use) Regulations 1986, any alteration to a vehicle’s original design must comply with strict safety standards. Insurance is not just a precaution—it’s a legal requirement for certain modifications, particularly those involving gas installations, electrical systems, or structural changes. Failing to secure coverage could result in fines, legal action, or even the inability to register the converted van for use on public roads.
- Liability protection: If your converted van causes damage to third parties (e.g., during transit or due to faulty modifications), insurance covers legal costs and compensation claims.
- Compliance with MOT and inspection rules: Insurers often require proof of compliance with UK vehicle safety standards, ensuring your conversion meets legal thresholds for roadworthiness.
- Financial security for repairs: Custom modifications can be costly to repair. Insurance mitigates expenses from accidents, theft, or vandalism, which are more likely for non-standard vehicles.
- Business continuity: For commercial conversions (e.g., mobile shops or work vans), insurance safeguards income by covering downtime or loss of equipment.
Ignoring insurance risks not only your investment but also public safety. Always verify your policy covers specific conversion elements, such as added weight, altered braking systems, or non-standard materials, to avoid gaps in protection.
Key Factors to Consider When Choosing Van Conversion Insurance
When selecting insurance for a van conversion project in the UK, focus on three critical areas: coverage limits, exclusions, and policy customization. Coverage limits must align with the total value of your conversion, including materials, fixtures, and any specialist equipment (e.g., refrigeration units or solar panels). Underinsuring can leave you financially exposed if damage occurs, so calculate the rebuild cost accurately. For example, a fully kitted-out campervan may require higher limits than a basic work van. Always verify that the policy covers both the vehicle’s original structure and all added modifications.
- Policy exclusions: Review what is not covered, such as unregistered modifications, off-road use, or damage from improper installation. Some insurers exclude coverage for conversions not completed by certified professionals.
- Tailored plans: Commercial conversions (e.g., mobile shops) need policies that include business liability and cargo coverage, while recreational conversions may prioritize theft or vandalism protection. Ensure the insurer understands your specific use case.
- Claims process: Choose providers with streamlined claims for conversions, as complex repairs may require specialist technicians. Check if the insurer has experience with similar projects.
For detailed guidance on policy customization, consult the Association of British Insurers’s resource on modified vehicle insurance, which outlines key considerations for UK policyholders.
Top Providers of Van Conversion Insurance in the UK
When selecting insurance for a converted van, prioritizing providers with expertise in specialized coverage is crucial. AXA stands out for its comprehensive policies that include modifications like electrical systems and custom fittings, paired with a streamlined claims process. Aviva offers tailored options for commercial and leisure conversions, with strong customer service noted in recent reviews. LV= is frequently recommended for its flexible policies that accommodate both part-time and full-time van living, alongside competitive pricing. Churchill Insurance provides robust coverage for high-value conversions, with a focus on protecting unique features such as solar panels or insulation. Admiral, meanwhile, appeals to budget-conscious converters with straightforward policies and quick underwriting.
- AXA: Ideal for complex conversions; covers bespoke modifications and offers 24/7 claims support.
- Aviva: Strong emphasis on customer service; policies include coverage for tools and equipment used in conversions.
- LV=: Affordable options for both residential and commercial use; includes breakdown assistance for remote locations.
- Churchill: High-value coverage for luxury conversions; detailed risk assessments during policy setup.
- Admiral: Simple, no-frills policies with fast approval times; suitable for basic conversions or first-time converters.
Before finalizing a policy, cross-reference your conversion plans with uk van conversion ideas to ensure your insurance aligns with your project’s scope, such as whether you’re prioritizing off-grid living or commercial use.
Comparing Coverage Options for Different Van Conversion Projects
Insurance policies for van conversions vary significantly based on the project’s complexity, materials, and intended use. A basic conversion—such as adding a sleeping area with standard materials—may require minimal coverage, while a high-end build with custom electrical systems, luxury finishes, or commercial equipment demands tailored policies. Insurers assess risk by evaluating the value of installed components; for example, a van fitted with expensive wood interiors or advanced HVAC systems may incur higher premiums due to increased replacement costs. Always review policy exclusions, as some insurers omit coverage for modifications like solar panels or off-grid power systems unless explicitly added.
- Project Scope: Large-scale conversions (e.g., full living quarters) often need comprehensive coverage for structural changes, while smaller projects may suffice with basic policies. Refer to best van conversion uk for guidance on balancing scope and budget.
- Materials Used: Policies may differentiate between standard and high-value materials. Insurers might charge extra for conversions using rare metals, glass, or bespoke furniture, as these are harder to replace.
- Intended Use: Commercial vans (e.g., mobile offices or shops) require coverage for business assets, liability, and income loss. Recreational conversions (e.g., campers) may need additional protection for towing equipment or off-road damage.
Compare quotes from insurers specializing in van conversions, and ensure your policy aligns with both the project’s unique features and its long-term use.
How to Claim and Manage Insurance for Van Conversion Projects
When filing a claim for van conversion insurance in the UK, begin by notifying your insurer immediately if damage occurs during the conversion process. Provide detailed photos of the affected area, along with a written description of the incident. Submit all required documentation, including your policy number, conversion project timeline, and proof of any modifications made (e.g., invoices for materials or permits). For claims related to theft or vandalism, include police reports or witness statements. Insurers may send an adjuster to assess the damage, so ensure all work is clearly marked with dates and progress notes.
- Documentation essentials: Keep copies of your original van’s valuation, conversion plans, and receipts for custom fittings or equipment. A certificate of compliance from a certified van conversion specialist may also be required for structural changes.
- Policy management: Review your policy annually to ensure coverage aligns with your project’s evolving needs. Add endorsements for high-value modifications (e.g., solar panels or refrigeration units) if not already included.
- Dispute resolution: If your claim is denied, request a detailed explanation from the insurer and appeal using the Financial Ombudsman Service (FOS) if necessary. Maintain a log of all communications and evidence.
- Ongoing communication: Inform your insurer of any delays or changes to the conversion schedule, as this may affect coverage terms or claims processing.
Regularly update your insurer on project milestones and store all paperwork digitally for easy access during claims. For complex conversions, consider consulting a specialist broker to tailor coverage to your specific modifications.
Leave a Reply